Letter of Credit in Spain: Documents, Discrepancies and Payment Risk
The draft letter of credit requires an inspection certificate issued by an “official independent” body and signed to confirm the buyer’s satisfaction. Nobody in the transaction has identified that body, and the inspection cannot happen early enough to meet the presentation period. Shipping against that wording would leave the exporter trying to cure an impossible document after the goods have moved.
Review each operative condition against a document producer, a delivery route and a deadline. Banks examine documents, not the goods or the underlying performance. A commercial safeguard that has not been translated into an obtainable documentary requirement may not work as the applicant expects.
Mark the issued text before anyone relies on it
The specimen below is entirely fictional. It is not a model MT700 and should not be copied into an application. Its purpose is to reveal dependencies while amendment is still possible.
| Field | Fictional entry | Question for the file | Status |
|---|---|---|---|
| 40E | UCP LATEST VERSION | Which rules and version are incorporated, and does another clause modify them? | Verify with issuer |
| 31D | Expiry at a presentation place outside the beneficiary’s usual route | Can the documents reach that place before expiry? | Amend before shipment |
| 41a | Available with a named bank by deferred payment | What is that bank’s role, and when is payment due? | Verify with issuer |
| 44C and 48 | Latest shipment date; presentation within five calendar days | Can the carrier, insurer and inspector issue and route their documents within the shorter period? | Amend before shipment |
| 46A | Invoice, transport and insurance documents, plus the inspection certificate | Who issues each one, what data must appear, and in what original, copy or electronic form? | Verify with issuer |
| 47A | Goods must meet the buyer’s specification, but no evidence document is stipulated | Is the commercial concern meant to affect document examination, and if so through which workable document? | Lawyer/bank to resolve |
| 49 | WITHOUT | Has any bank actually added confirmation, or is it only advising or nominated? | Verify with issuer |
| 71D | Charges allocated only in part | Who bears issuance, advising, amendment, discrepancy, courier and any confirmation charges? | Verify with issuer |
A working feasibility sheet should also record the document producer, earliest issue date, required data, format, delivery path and last safe action date for each row. The answer should be one of four restrained outcomes: workable, verify with issuer, amend before shipment, or lawyer/bank to resolve. It should not purport to be an amendment request or a compliance opinion.
UCP applies through the credit
UCP 600 is not Spanish legislation. It binds the relevant parties when the credit expressly states that it is subject to UCP, except to the extent the credit modifies or excludes a rule. Read the incorporation wording and the rest of the instrument together. Under UCP, the credit is separate from the sale contract, and banks deal with documents rather than goods, services or performance. These points appear in UCP 600 articles 1, 4 and 5.
Documentary compliance and commercial performance answer different questions. A complying presentation does not prove that the goods conform to the sale contract. An unstipulated commercial condition may not create a documentary discrepancy. Article 14(h) treats a condition as not stated when the credit contains no document indicating compliance. Article 14(f) provides a limited examination rule for certain required documents when the credit does not specify the issuer or data. Ask whether the intended producer can issue the stated document with the required content.
Three dates are not one deadline
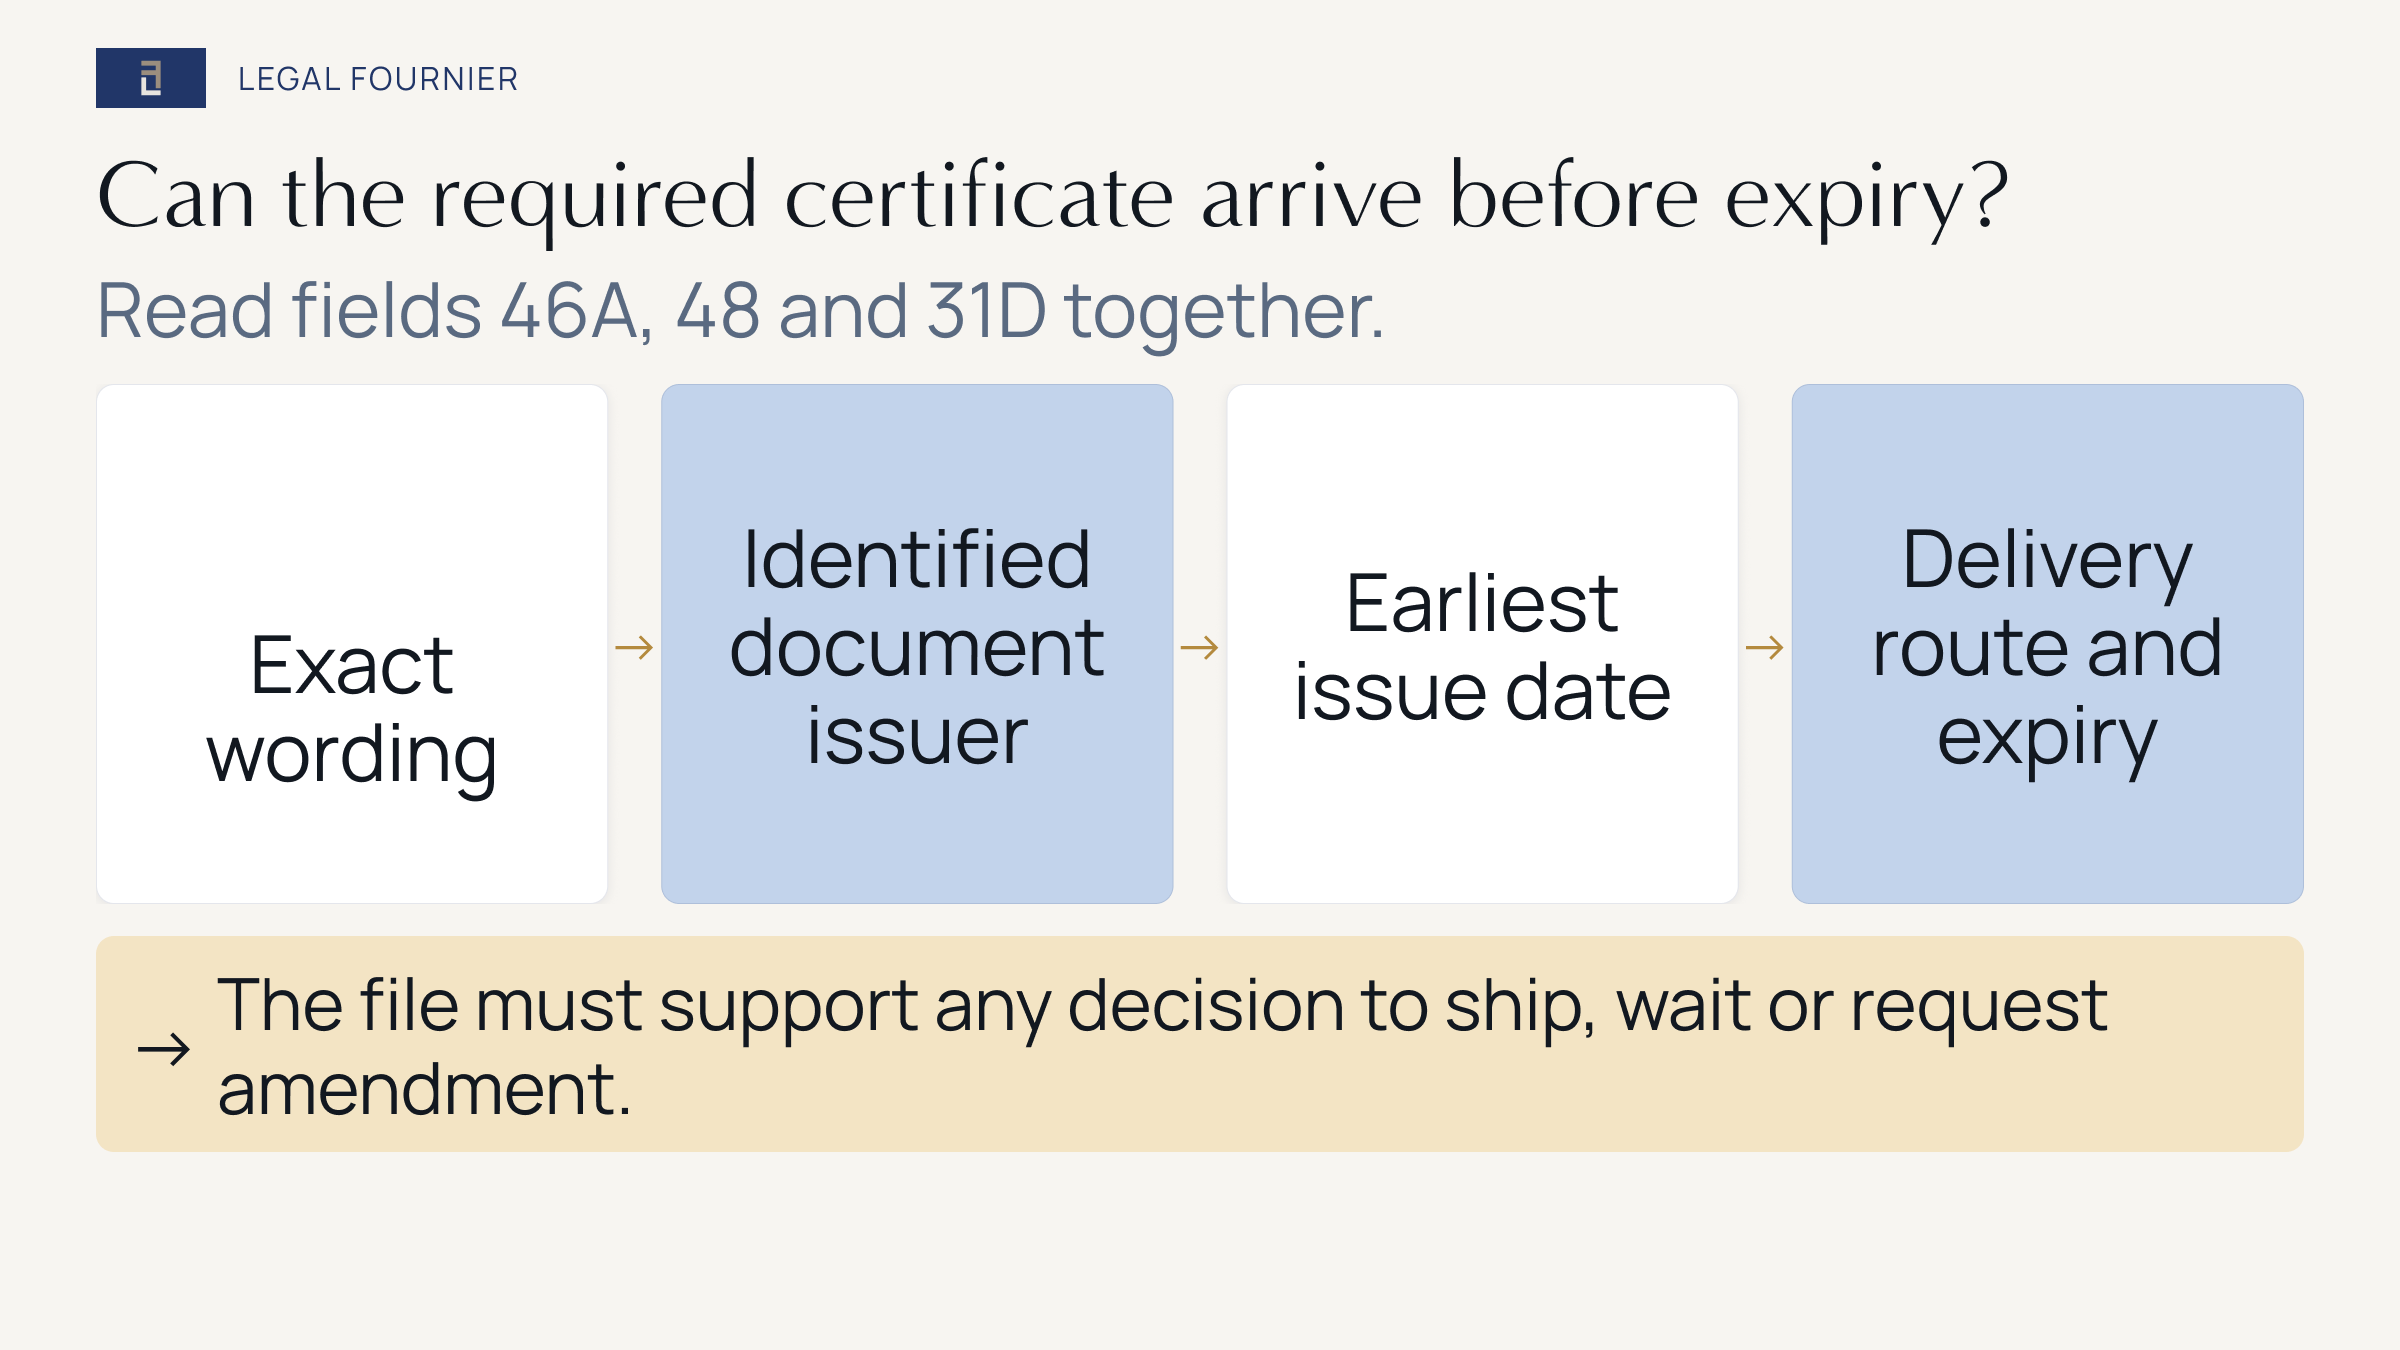
Field 44C, field 48 and field 31D must be tested together. They address shipment, the period for presenting documents and expiry. Under UCP 600 article 14(c), a presentation containing one or more original transport documents governed by articles 19 to 25 must be made no later than 21 calendar days after shipment and, in all cases, no later than expiry. That 21-day provision is not a universal allowance. The credit may state a shorter presentation period, as the fictional specimen does.
Article 14(a) gives an examining bank a maximum of five banking days after presentation to decide whether the documents comply. That is the bank’s examination period. It does not extend the beneficiary’s expiry or presentation deadline. Keep banking and calendar days distinct in the file.
Classify each bank by the issued instrument
An issuing bank gives the undertaking described in the credit. An advising bank that has not confirmed does not undertake to honour or negotiate merely because it passes the credit to the beneficiary. Nomination alone does not generally oblige the nominated bank to honour or negotiate. A confirming bank adds its own definite undertaking. Those roles have distinct meanings under UCP 600 articles 2, 8, 9 and 12.
Confirmation therefore has to be found in the operative text, not inferred from the presence of a second bank. Cost, availability and the remaining bank or country exposure are separate questions. Banco de España presents documentary credit as a payment instrument that can add collection and payment security in international business, but this does not turn every issued credit into unconditional payment. Its orientation for businesses is available through the Banco de España SME portal.
An amendment request is not an amendment
Once issued, a UCP credit cannot be amended or cancelled simply because the applicant asks for a change. UCP 600 article 10 requires the agreement of the issuing bank, any confirming bank and the beneficiary, subject to the article’s detailed acceptance rules. Pending acceptance, the original terms remain in force for the beneficiary. Record the request, issued amendment, advice and beneficiary response separately.
If documents have already been presented, preserve the bank’s notice exactly as received. UCP 600 article 16 requires a refusal notice to identify every discrepancy and state what is being done with the documents, within the prescribed time. An issuing bank or confirming bank that fails to comply with the article may be precluded from claiming non-compliance. That procedural point does not decide whether the applicant should waive a discrepancy or how a dispute will end.
Keep one transaction file, but separate three lanes
| Lane | Documents to reconcile | Question | Boundary |
|---|---|---|---|
| Commercial performance | Sale contract, specification, Incoterm, inspection arrangement and shipment plan | Has each commercial concern been converted into obtainable evidence where the credit needs it? | The bank does not inspect the goods. |
| Documentary credit | Issued credit, amendments, advice, stipulated documents, presentation receipt and refusal notice | Can the beneficiary make a complying presentation at the required place and time? | An applicant request is not an issued amendment, and nomination is not confirmation. |
| Tax, accounting and controls | Invoice, customs/export proof, VAT file, currency terms and sanctions/export-control facts | Which issues need a separate specialist review? | Documentary compliance does not decide VAT, accounting, FX exposure or permission to trade. |
Incoterms 2020 allocates delivery tasks, costs and risks under eleven business-to-business trade terms. It does not set the credit’s presentation conditions. See the ICC Incoterms rules. In the same way, a complying presentation does not itself establish a Spanish export VAT exemption. Article 21 of the Spanish VAT Act applies only when its transaction and evidence conditions are met.
A foreign-currency credit is not automatically an FX hedge. Spanish PGC NRV 11 uses the spot rate on the transaction’s recognition date for initial conversion and requires later treatment of monetary items under its own rules. The credit payment date may differ from the sale, VAT or accounting recognition date. The accountant should classify the actual balances and any separate hedge under the Spanish General Accounting Plan.
For an electronic presentation, do not assume that emailing a PDF is enough. eUCP applies only if the credit indicates that it is subject to that supplement and identifies the version. Its rules address electronic records, presentation place, format and notice of completeness. See ICC eUCP Version 2.1.
This article is general information. Documentary-credit, contract, sanctions, customs, tax, accounting, governing-law and dispute questions require review of the actual instrument and transaction.